Keynote Speakers
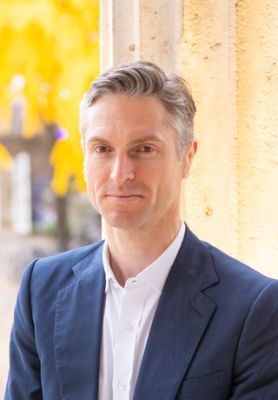
Professor Timothy Christensen
Yale University
Econometric Theory Lecture
Timothy Christensen is a Professor of Economics at Yale University. Before joining Yale, he was a Professor of Economics at University College London. He received a Ph.D. in Economics from Yale in 2014. His research interests lie broadly across theoretical and applied econometrics, financial econometrics, and statistics/data science. His most recent research is at the intersection of econometrics and machine learning, where he works on the integration of unstructured data into quantitative economic modelling. He has been awarded grants by the National Science Foundation and the European Research Council.
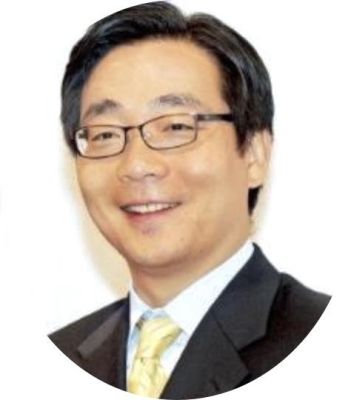
Professor Sokbae (Simon) Lee
Columbia University
2027 SETA Lecture
Sokbae (Simon) Lee is a Professor of Economics at Columbia University. Before joining Columbia, he was a Professor of Economics at Seoul National University and held faculty positions at University College London. He received his Ph.D. in Economics from the University of Iowa in 2002. His research interests lie in microeconometrics, econometric theory, and causal inference. His recent research centers on the intersection of econometrics and machine learning, focusing on optimal treatment allocation, high-dimensional estimation, and algorithmic decision-making. He is an elected Fellow of the Econometric Society and an elected Fellow of the Journal of Econometrics.
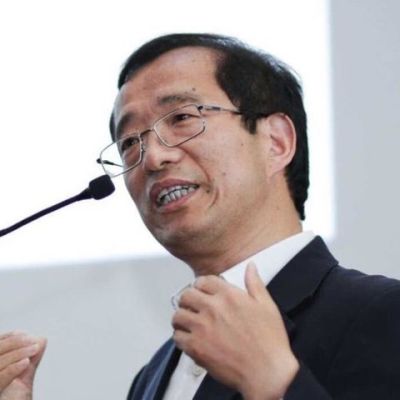
Professor Jiti Gao
Monash University
Jiti Gao is the Donald Cochrane Chair in Business and Economics and a Professor of Econometrics at Monash University. He received his PhD in Statistics from the University of Science and Technology of China and then PhD in Econometrics from Monash University. His research interests lie in theoretical and applied econometrics, including nonparametric and semiparametric methods, nonlinear time series analysis, and large panel data models. His research has been supported by continuous Australian Research Council grants. He is an elected Fellow of the Academy of the Social Sciences in Australia and an elected Fellow of the Journal of Econometrics.
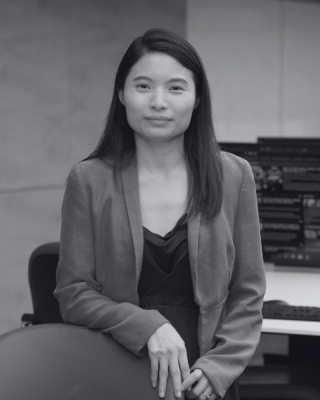
Professor Shuping Shi
Macquarie University
Shuping Shi is a Professor of Economics at Macquarie University. Before joining Macquarie, she was a Lecturer at the Australian National University. She received a Ph.D. in Econometrics from the Australian National University in 2011. Her research interests lie in financial econometrics, time series analysis, and applied economics. Her research focuses on econometric methodology for real-time bubble detection, high-frequency financial data modeling, and housing market dynamics. She is the recipient of the 2022 Young Economist Award from the Economic Society of Australia, and her work has been supported by multiple Australian Research Council grants, including a Discovery Early Career Researcher Award.
Professor Liangjun Su
Tsinghua University
Liangjun Su is the C.V. Starr Chair Professor of Economics in the School of Economics and Management at Tsinghua University. Before joining Tsinghua, he was the Lee Kong Chian Professor of Economics at Singapore Management University. He received a Ph.D. in Economics from the University of California, San Diego in 2004. His research interests lie broadly across theoretical econometrics, nonparametric and semiparametric methods, and financial econometrics. His recent research focuses on high-dimensional panel data analysis, latent group structures, and the intersection of econometrics and machine learning. He is an elected Fellow of the Journal of Econometrics.